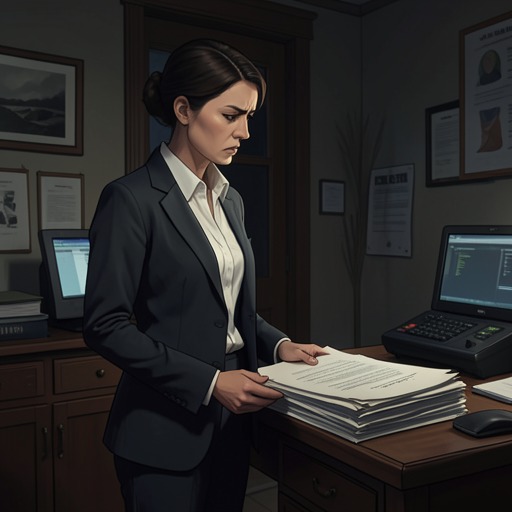
Elsa Lübing, the former chief accountant
Smilla's Sense of SnowElsa Lübing, the former chief accountant, is both a custodian of corporate records and a witness to how those records can conceal power. Through her account of the Cryolite Corporation of Denmark, she helps Smilla trace the overlap of public authority, private business, and confidential financial decisions; her own career is marked by a struggle to make the company’s procedures answer to conscience.
Identity and Introduction
Smilla first encounters Elsa through a letter among Juliane Christiansen’s papers. The letter grants Juliane a monthly widow’s pension of 9,000 kroner after the death of Norsaq Christiansen and bears the signature “E. Lübing, Chief Accountant.” In the margin, someone has added an apology and signed it in full: “I am so sorry. Elsa Lübing.” The juxtaposition of formal corporate language and private regret introduces Elsa as a figure whose personal judgment has left a trace inside an official document.
When Smilla eventually visits, Elsa studies her before inviting her in. She is described as tall, dressed simply, with a silver cross and no other jewelry. The impression is of a composed, guarded person, fitting for someone whose knowledge is protected by layers of company procedure and whose decision to assist Smilla will require a breach of those procedures.
Conscience and Corporate Reform
Elsa says she used her influence within the company to increase contact with Greenlanders. At the Saqqaq quarry, as at the quarry operated by the Øresund Cryolite Corporation in Ivittuut, work had been divided along a strict line: Danish employees held the jobs, while Greenlanders were hired only as cleaners. Elsa invoked the commandment to love one’s neighbor and sought to change the relationship between the company and Greenlandic workers.
Her account of the pension for Norsaq Christiansen connects that effort to Juliane and her son, Isaiah. The company had hired Greenlanders for occasional geological expeditions, and Norsaq had continued supporting his wife and child after his wife left him. When the board awarded Juliane the pension, Elsa invited her and Isaiah to her office. Asked whether the company had a legal obligation to pay, Elsa says there probably was none, though she cannot rule out that her advice influenced the decision. The pension letter’s apologetic marginal note gives that institutional act a personal dimension.
Elsa also challenged the company’s internal social divisions. When she became chief accountant on May 17, 1957, the company had six separate cafeterias, divided by occupational rank and status, from workers to directors. She raised the arrangement with social-welfare minister Steincke, arguing from the example of the first Christian congregation, where people shared what they had with the poor and lived together as brothers and sisters. Steincke answered with a biblical distinction between what belonged to God and what belonged to Caesar. Years later, the company had only one cafeteria. Elsa presents the change as a consequence of pressure on a hierarchy that had seemed ordinary to its inhabitants.
Records, Authority, and the Missing Money
The company was partly state-supported: the government owned 33.33 percent of its shares and had a representative on the board. Copies of records were made using photostats, and parts of the accounts were examined by the Audit Department, later renamed the National Bureau of Auditing. Yet these safeguards did not make the accounts fully transparent. Cooperation with private-sector partners and the division of authority created complicated arrangements, while certain sections of the books remained inaccessible even to Elsa. She kept her own ledgers in gray moleskin bindings stamped in red and says there was also a smaller, confidential ledger.
Elsa describes how responsibility was concentrated in practice. The finance director was also the board’s executive chairman, while other senior figures were often away from the quarry or traveling. In her view, the finance director consequently made most important decisions for many years. The company’s widely dispersed shares—held by the heirs of eight original mineral-rights partners—made it difficult to assemble a general stockholders’ meeting. Auditors were chosen at such meetings, and the corporation was a major customer; an auditor who opposed its director risked losing the business. Institutional oversight existed, but personal influence and commercial dependence weakened it.
On January 7, 1967, while balancing the semiannual accounts, Elsa found an unitemized entry for 115,000 kroner. The sum was large, and the file card that should have explained it was missing. She brought the matter to the finance director, whom she had served for twenty years. He told her that he had authorized the entry for technical bookkeeping reasons, that the auditor considered the listing acceptable, and that the issue was beyond her expertise. Elsa does not describe the ultimate destination of that money in this exchange; what she establishes is the missing documentation, the director’s control over the decision, and the limits placed on her scrutiny.
The 1991 Accounts and the Archive
In 1977 the company computerized its accounts, but Elsa never learned to understand the system and arranged to keep manual records as well. She retired in 1992. Three weeks before her final workday, she insisted on balancing the books herself rather than leaving the task to the office manager. On January 7, exactly twenty-five years after the unexplained 1967 entry, she compared the old accounts with those for the previous summer’s expedition to Gela Alta.
The 1991 expedition was financed through the Scientific Commission, a funding arrangement that had become common. Elsa found that its largest entry was 450,000 kroner and called the commission to request an itemization. A later letter rebuked her for going over her immediate superiors’ heads, but she says the answer had already been given to her by telephone: the money had been used to charter a ship. Her persistence links the old accounting irregularity to a later expedition and a substantial, initially unexplained shipping expense, while the official reprimand demonstrates the pressure to keep questions within designated channels.
Elsa ultimately tells Smilla that the company has two archives in the basement of its building on Strand Boulevard. The first contains accounts and correspondence and is accessible to supervisors, bookkeepers, Elsa, and sometimes department heads. Behind it lies the second archive, restricted in principle to those with permission from the board or director. It holds expedition reports, mineral samples, topographical maps, and drilling cores. By disclosing the archive’s location and contents, Elsa turns her access to corporate records into an active contribution to Smilla’s investigation.
Narrative Role and Significance
Elsa’s testimony makes the company’s paperwork more than background: ledgers, missing file cards, confidential books, and restricted archives become evidence of how authority is exercised and information controlled. Her story distinguishes formal accountability from effective oversight. Government ownership, auditors, and public records coexist with private influence, divided access, and decisions shielded by commercial relationships.
Her actions are neither a wholesale rejection of the corporation nor simple obedience to it. She challenges the segregation of workers, supports a pension for Juliane, questions unexplained expenditures, and finally helps Smilla reach the archive. Across these episodes, her ethical commitments take the form of practical interventions—changing a cafeteria arrangement, requesting an itemization, and opening a door that the company’s rules would normally keep closed. The apologetic note in Juliane’s pension letter and the restricted records in the basement frame two sides of Elsa’s role: personal responsibility expressed within an institution, and evidence made accessible despite its barriers.